Tag Archives: compound interest

HUMANITY’S DANGEROUS EXPONENTIAL BLIND SPOT

Fifty years ago, a highly respected American physicist warned: “The greatest shortcoming of the human race is our inability to understand the exponential function.” Today, his caution is more relevant than ever as technology advances, demands on resources mount, and changes that once took centuries or decades can happen in years. Sometimes months… or days. Yet humanity’s blindspot is ignoring the dangers of exponential increase or the power of compounding growth.

Professor Albert Bartlett taught physics at the University of Colorado and spent years explaining a simple mathematical principle that even impressively educated people frequently underestimate. He believed humanity’s failure to understand compounding function was leading us toward serious problems that could’ve been anticipated and possibly/probably prevented.

Today, we’re witnessing extraordinary advances in artificial intelligence, computing, medicine, and scientific discovery. Some of these developments are compounding at remarkable rates, bringing enormous opportunities along with equally significant challenges. The trouble is that we aren’t very good at recognizing where these changes may take us.

But Bartlett’s message wasn’t all doom and gloom, and neither is the future. Understanding exponential growth can help us recognize dangers, anticipate change, and take advantage of opportunities that previous generations could scarcely have imagined. And as we’ll discover, the mathematics concealed in humanity’s dangerous blind spot is surprisingly simple.

The World Is Changing Faster Than We Can Understand It

Think back to when the internet came through a telephone line and the modem sounded like it was trying to contact Mars. In a single working lifetime, we’ve moved from waiting for a webpage to load to carrying much of the world’s accumulated knowledge in our pockets. Now artificial intelligence can analyze information, generate explanations, and write computer code in seconds. That’s astonishing progress, but the real problem isn’t speed alone.

What gets us into trouble is treating tomorrow as a slightly larger version of today. When something grows by a fixed percentage, each increase builds on a bigger base. For a while, the difference hardly seems worth mentioning. Then it becomes impossible to ignore, and by the time the consequences become obvious, opportunities to deal with them may have passed.

This matters far beyond computers. Compound interest can quietly build a retirement fund or bury a household in debt. A contagious disease can spread faster than a healthcare system can respond. Growing demands for energy, water, and other resources can overwhelm infrastructure designed around yesterday’s expectations. Not everything grows exponentially, of course, and nothing physical can continue doing so indefinitely. But failing to recognize compounding growth can come at an enormous cost.

There’s an encouraging side to all this. Understanding exponential growth isn’t particularly difficult, and it doesn’t require an advanced mathematics degree. What it does require is learning to look beyond what’s happening today and recognize what might happen tomorrow. That’s the lesson one remarkably persistent physics professor spent much of his life trying to teach.
The Professor Who Tried to Warn the World

Albert Allen Bartlett wasn’t an alarmist who’d discovered a catchy line. He was a physicist with a Harvard doctorate who’d worked at Los Alamos during the Manhattan Project before joining the University of Colorado in 1950. He taught there for decades, became president of the American Association of Physics Teachers, and earned a reputation as a gifted teacher. But the work he’d become best known for had less to do with advanced physics than elementary arithmetic.

On September 19, 1969, Bartlett gave a lecture to university students called Arithmetic, Population and Energy. His concern was that politicians, business leaders, and ordinary citizens kept talking about steady growth as though it could carry on forever. Population was increasing, energy consumption was rising, and apparently sensible projections were ignoring what happens when one year’s growth gets added to the next. The numbers weren’t complicated. Their consequences were.

Bartlett took that lecture on the road and eventually delivered it 1,742 times, across 49 American states and seven other countries. Think about that. A respected scientist spent much of his life repeating essentially the same lesson because he believed people still weren’t getting it. He wasn’t arguing that every kind of progress was bad. He was warning that growing demands on finite resources couldn’t continue indefinitely at a fixed percentage rate, regardless of how comfortable the early numbers looked.

Bartlett died in 2013 at ninety, but the problem he identified didn’t retire with him. We’re now surrounded by growth figures, projections, and technological forecasts that are easy to repeat and much harder to understand. His lasting contribution wasn’t inventing the exponential function. It was insisting that we learn what it actually means before making decisions based on it. And the place to start is with the deceptively simple mathematics.
The Mathematics That Fools Almost Everyone

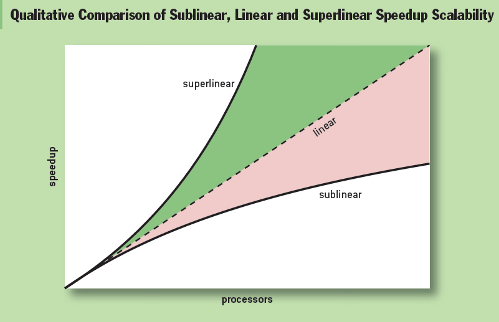
The mathematics behind exponential growth isn’t particularly difficult. Most of us understand that adding ten to a number makes it ten larger. That’s linear growth, where the same amount gets added each time. Exponential growth works differently because each increase is calculated on the new, larger total. The percentage stays the same, but the amount being added keeps growing. That’s where our intuition often lets us down.

Let’s say you start with 100 dollars and add five dollars every year. After thirty years, you’ll have 250 dollars. But if that original 100 dollars grows by five percent annually, with each year’s earnings added to the total, you’ll have approximately 432 dollars after thirty years. The difference comes from compounding, where growth earns further growth. It’s the same principle that makes compound interest so valuable to investors and so expensive to people carrying unpaid debt.

Bartlett frequently explained exponential growth using the Rule of 70, a simple mathematical shortcut for estimating doubling time. Divide 70 by the annual percentage growth rate and you’ll get approximately how many years it’ll take something to double. At seven percent growth, that’s about ten years. After twenty years, the original amount has roughly quadrupled, and after thirty it’s approaching eight times its starting value. Nothing magical has happened. The mathematics has simply been doing its work.

Here’s what makes this so deceptive. During the early stages, exponential growth can appear almost insignificant, especially when the starting amount is small. By the time the increases become impossible to ignore, the process may have been underway for years. Of course, nothing in the physical world can grow exponentially forever, but understanding how quickly things can change before reaching their limits is essential. Bartlett had a favourite illustration involving a chessboard and a few grains of wheat. It’s a story worth telling because the numbers become almost unbelievable.

What is the exponential function, and how does exponential growth work? The exponential function describes a quantity that changes by a constant multiplying factor over equal intervals. Unlike linear growth, which adds the same amount each time, exponential growth compounds on an increasingly larger base. For example, $100 growing at seven percent annually becomes approximately $197 after ten years. The Rule of 70 provides a simple way to estimate doubling time: divide 70 by the annual percentage growth rate.

The King, the Chessboard, and the Grain of Rice

Bartlett had a favourite story that illustrated exponential growth better than any mathematical formula. According to an ancient legend, a king was so pleased with the invention of chess that he offered its creator whatever reward he wanted. The inventor made what seemed like a ridiculously modest request. He wanted one grain of rice placed on the first square of a chessboard, two grains on the second, four on the third, eight on the fourth, and so on, doubling the amount on each successive square until all sixty-four were covered.

The king must’ve thought he’d struck a pretty good bargain. After all, how much could a few grains of rice possibly cost? But the inventor understood something the king didn’t. The first ten squares required only 1,023 grains in total. By the twentieth square, the total exceeded a million, and by the thirtieth, it had passed a billion. Things were getting expensive.

Now comes the astonishing part. By the sixty-fourth square, the king would’ve needed 9.2 quintillion grains for that square alone. The total for the entire chessboard would’ve been approximately 18.4 quintillion grains, or 18,446,744,073,709,551,615 to be precise. Depending on the size of the grains, that’s hundreds of billions of tonnes of rice. The royal treasury wasn’t going to cover that bill.

Bartlett used wheat rather than rice in his telling, but the lesson was identical. Each new square required one grain more than the combined total of every preceding square. Think about that. After sixty-three doublings, the final increase was greater than everything that had accumulated before it. That’s the extraordinary mathematical power of compounding, and it explains why apparently manageable growth can eventually produce overwhelming consequences.

The chessboard is only a legend, but the arithmetic is indisputable. The unsettling question is why something so straightforward remains so difficult for intelligent people to appreciate when the numbers involve real money, resources, populations, or technological change.
Why Our Brains Keep Getting the Future Wrong

The king’s mistake wasn’t that he couldn’t do arithmetic. He simply couldn’t imagine where all that doubling would lead, and he’s hardly alone. Most of us make judgments about the future based on what we’ve experienced in the past. If something’s been changing slowly, we tend to expect more of the same. That works reasonably well for many everyday situations, but it can get us into serious trouble when growth starts compounding.

Psychologists have studied this tendency for decades and given it a name: exponential-growth bias. Research consistently shows that people underestimate how quickly quantities increase when they’re growing by a fixed percentage. In a 2022 study involving 521 participants, researchers found that people were reasonably accurate at predicting straight-line growth but regularly underestimated exponential trends. Mathematical knowledge helped, although even understanding the principle doesn’t always prevent us from making the mistake.

There’s another problem. We’re often more confident in our predictions than the evidence warrants. During the COVID-19 pandemic, for example, many people had difficulty appreciating how quickly infections could multiply before hospitals became overwhelmed. Researchers found that helping people understand exponential growth changed their perception of the danger. What seemed manageable one week could become a public health emergency shortly afterward.

None of this means humans are incapable of understanding exponential change. It means our first impressions aren’t always reliable, particularly when we’re dealing with unfamiliar numbers and long-term projections. The sensible approach is to question our assumptions, examine the actual growth rates, and do the arithmetic rather than trust our instincts. That’s especially important when the consequences involve something more substantial than a king’s imaginary rice bill.

Why do humans have difficulty understanding exponential growth? Humans tend to judge the future by extending familiar patterns from the past, which makes the accelerating effects of compounding difficult to appreciate. Physicist Albert Bartlett warned that this misunderstanding leads societies to underestimate the consequences of population growth and increasing resource consumption. The classic chessboard illustration demonstrates the problem: doubling one grain on each successive square produces more grains on the sixty-fourth square than on all sixty-three preceding squares combined.

Exponential Growth Isn’t Just a Mathematical Curiosity

Bartlett wasn’t particularly concerned about chessboards or imaginary rice bills. He was worried about what happens when people fail to recognize exponential growth in the real world, where the consequences can affect their finances, health, resources, and future. Consider compound interest. Money invested at a reasonable rate of return can grow substantially over several decades because the earnings themselves generate further earnings. But the same principle works against anyone carrying unpaid credit card debt. Compounding doesn’t care whether you’re getting richer or poorer.

Infectious diseases provide another sobering example. During the early stages of an epidemic, when most people remain susceptible, infections can multiply exponentially as each infected person passes the disease to others. That’s why apparently small outbreaks can develop into major public health emergencies before authorities have time to respond. The good news is that infections don’t keep multiplying indefinitely. Immunity, changing behaviour, medical interventions, and other factors can slow or reverse the spread.

Population growth was Bartlett’s principal concern. The world’s population reached approximately one billion around 1800 and passed eight billion in 2022. But here’s an important distinction. Global population isn’t currently growing exponentially at a constant rate. Growth rates have been declining for decades, and United Nations projections suggest the population could peak at approximately 10.3 billion during the 2080s. That’s a reminder that growth rates change, and projections aren’t guarantees.

Nevertheless, Bartlett’s warning about finite resources remains relevant. Increasing populations and rising consumption can place enormous demands on energy, water, food production, and infrastructure. Technological improvements can expand supplies and increase efficiency, but they can’t abolish physical limits. The challenge is understanding how demand, resources, innovation, and time interact before shortages or other consequences become serious.

And there’s another side to this equation. The same mathematics that compounds financial burdens and resource demands can help produce extraordinary advances in science and technology. We’re now witnessing developments in artificial intelligence that would’ve seemed like science fiction a generation ago. That brings Bartlett’s half-century-old warning directly into the world we’re living in today.
Artificial Intelligence: Exponential Growth Meets the Twenty-First Century

If Albert Bartlett were alive today, he’d have a fascinating new subject for his lecture. When he first warned about exponential growth in 1969, computers filled rooms, the internet was in its infancy, and artificial intelligence was largely confined to research laboratories. Today, AI systems can write computer programs, analyze complex information, solve advanced mathematical problems, and assist scientists with discoveries that would’ve taken years using conventional methods. And the technology’s improving at a pace that’s difficult to comprehend.

Consider what Stanford University’s annual AI Index has documented. Its 2025 report found that the computing power used to train notable AI models had been doubling approximately every five months. Meanwhile, the cost of running a model capable of performing at a benchmark level comparable to GPT-3.5 fell more than 280-fold between November 2022 and October 2024. In other words, we’re developing increasingly powerful technology while making many of its capabilities dramatically cheaper and more accessible.

Stanford’s 2026 report paints an equally remarkable picture. Artificial intelligence reached 53 percent adoption within three years, according to the report’s global adoption measure, considerably faster than personal computers or the internet achieved comparable penetration. AI systems designed to operate computers independently improved their success rate on one established benchmark from approximately 12 percent to 66 percent in a single year. That’s substantial progress, although it also means those systems were still failing roughly one-third of the tested tasks.

But here’s where we need to apply some of Bartlett’s mathematical discipline. Not every improvement in artificial intelligence follows a consistent exponential curve, and nobody can confidently predict how long present rates of advancement will continue. Some capabilities are improving extraordinarily quickly, while others remain frustratingly unreliable. An AI system might solve an advanced mathematical problem yet struggle with something a reasonably competent human would find straightforward. Technological progress doesn’t always follow a smooth or predictable path.

What makes this development particularly significant is how improvements can reinforce one another. Better computing equipment enables more ambitious research, improved algorithms make existing hardware more productive, and cheaper AI services encourage wider adoption and further investment. The potential benefits for medicine, education, scientific research, and economic productivity are enormous, but so are the challenges of adapting to changes occurring faster than many institutions can respond.

Bartlett would’ve recognized both the mathematics and the warning signs. What we’re witnessing isn’t simply another technological invention. It’s a rapidly evolving collection of capabilities that could fundamentally change how humanity learns, works, discovers, and solves problems. But even the most sophisticated artificial intelligence depends on something decidedly old-fashioned: electricity, physical resources, and the infrastructure needed to keep it running.

Is artificial intelligence advancing exponentially, and what are the consequences? Some aspects of artificial intelligence have advanced at approximately exponential rates over particular periods, including the computing power used to train leading AI models. However, AI capability, affordability, and adoption don’t follow one universal exponential curve. Physical resources, electricity, computing infrastructure, and technological limitations constrain progress. Understanding these trends helps societies anticipate potential disruptions while recognizing opportunities for scientific discovery, improved healthcare, education, and greater human capability.

When Exponential Progress Meets Physical Reality

Artificial intelligence might seem almost magical when we’re sitting at a computer watching it perform tasks that would’ve been impossible a few years ago. But behind every AI interaction is an enormous physical infrastructure of computer chips, servers, data centres, electrical grids, and cooling systems. These machines consume electricity, generate heat, and require substantial resources to manufacture and operate. The digital world might appear limitless, but it still has to obey the laws of physics.

According to the International Energy Agency, the world’s data centres consumed approximately 485 terawatt-hours of electricity in 2025. That’s expected to nearly double to 950 terawatt-hours by 2030, representing roughly three percent of global electricity demand. These figures include conventional data centres as well as those dedicated to AI, but artificial intelligence is a major driver of the increase. And those numbers are projections, not guarantees.

Here’s where things get complicated. Software can improve almost overnight, but building power plants, manufacturing electrical transformers, and expanding transmission networks can take years. Data centres also need water or other cooling arrangements, suitable locations, and access to reliable power. In some regions, rapidly increasing demand could strain electrical grids, raise costs, and compete with other essential infrastructure requirements. You can’t solve every physical problem with a software update.

There’s another interesting twist. As computer chips and AI algorithms become more efficient, individual tasks often require less electricity. That’s encouraging, but cheaper technology can also encourage greater use, and increasingly sophisticated applications may consume substantially more energy. Improvements in efficiency don’t necessarily translate into lower overall consumption. It’s another example of why understanding the interaction between growth and resources matters.

Bartlett would’ve recognized this conflict immediately. Exponential progress in one area doesn’t mean everything supporting it can expand at the same rate. Physical limits, economic realities, and human decisions all influence how far and how quickly technology can advance. But those constraints don’t mean progress has to stop. In fact, artificial intelligence might help us overcome some of the very problems its rapid development is creating.
The Other Side of the Exponential Curve

After looking at the growing demands on energy and natural resources, it’d be easy to conclude that exponential growth is mostly bad news. It isn’t. The same mathematics that can turn a small problem into a major headache can also magnify the benefits of scientific discovery, education, and technological progress. One improvement creates opportunities for another, and before long we’re doing things that would’ve seemed impossible a generation ago.

Take medical research. Google’s DeepMind developed an artificial intelligence system called AlphaFold that’s helped scientists predict the structures of hundreds of millions of proteins. That’s information researchers can use to better understand diseases and investigate potential treatments. It doesn’t mean AI has suddenly cured everything, but it’s opened possibilities that would’ve required enormous amounts of conventional research.

Or consider weather forecasting. European researchers have developed AI systems that can outperform traditional forecasting methods on several important measures, including predicting storm tracks. Better forecasts can’t stop a hurricane, but they can give people more time to prepare. In education, AI can provide personalized explanations and learning assistance that would’ve been difficult or expensive to obtain just a few years ago.

And here’s where things become particularly interesting. Artificial intelligence isn’t simply another invention that makes existing tasks faster. It can help humans investigate problems, test ideas, develop knowledge, and improve the very methods we use to make further discoveries. That creates the possibility of progress building on progress, although it doesn’t guarantee that every advance will produce another.

Of course, none of this happens automatically. Technology can make mistakes, create dependencies, and produce unintended consequences. Human judgment, critical thinking, and responsible decisions remain essential. But understanding exponential growth gives us something more valuable than the ability to predict trouble. It gives us an opportunity to recognize possibilities, prepare for change, and deliberately influence the future we’re creating.

Understanding the Curve Before It Overtakes Us

Albert Bartlett spent decades trying to get one simple message across. Exponential growth isn’t difficult to calculate, but its consequences can be extraordinarily difficult to imagine. He wasn’t asking everyone to become a mathematician. He wanted us to recognize the pattern, question our assumptions, and understand what might happen before it’s too late to do something about it.

That’s particularly important today as artificial intelligence and other technologies change how we live, work, and understand the world. We can’t predict the future simply by extending a mathematical curve, but we can become better at recognizing emerging problems and extraordinary opportunities.

There’s every reason to be optimistic about what lies ahead, provided we approach change with knowledge, curiosity, and sound judgment. Bartlett’s warning wasn’t a declaration that humanity was doomed. It was a reminder that understanding reality gives us a better chance of shaping our future rather than being overtaken by it.
Dyingwords.net is a node of Centaur Intelligence Systems and Twenty-Second Century Enlightenment – 22ENL.
centaursystems.ai
The Valley, Anguilla

THE MAGIC OF SUPERLINEAR RETURNS

This is not a regular, bi-weekly Dyingwords post. It’s a special edition, and it’s an essay written by Paul Graham in October 2023 who shared it Farnam Street which is a critical thinking site I’ve followed for a long time. The topic is about superlinear returns, a concept of compounding growth. I feel it’s so important for long-term personal development to understand what superlinear returns are and how you can work this “magic” to your full advantage. Here’s Mr. Graham explaining superlinear returns.

One of the most important things I didn’t understand about the world when I was a child is the degree to which the returns for performance are superlinear.

Teachers and coaches implicitly told us the returns were linear. “You get out,” I heard a thousand times, “what you put in.” They meant well, but this is rarely true. If your product is only half as good as your competitor’s, you don’t get half as many customers. You get no customers, and you go out of business.

It’s obviously true that the returns for performance are superlinear in business. Some think this is a flaw of capitalism, and that if we changed the rules it would stop being true. But superlinear returns for performance are a feature of the world, not an artifact of rules we’ve invented. We see the same pattern in fame, power, military victories, knowledge, and even benefit to humanity. In all of these, the rich get richer. [Note 1]

You can’t understand the world without understanding the concept of superlinear returns. And if you’re ambitious you definitely should, because this will be the wave you surf on.

It may seem as if there are a lot of different situations with superlinear returns, but as far as I can tell they reduce to two fundamental causes: exponential growth and thresholds.

The most obvious case of superlinear returns is when you’re working on something that grows exponentially. For example, growing bacterial cultures. When they grow at all, they grow exponentially. But they’re tricky to grow. Which means the difference in outcome between someone who’s adept at it and someone who’s not is very great. Startups can also grow exponentially, and we see the same pattern there. Some manage to achieve high growth rates. Most don’t. And as a result you get qualitatively different outcomes: the companies with high growth rates tend to become immensely valuable, while the ones with lower growth rates may not even survive.

Y Combinator encourages founders to focus on growth rate rather than absolute numbers. It prevents them from being discouraged early on, when the absolute numbers are still low. It also helps them decide what to focus on: you can use growth rate as a compass to tell you how to evolve the company. But the main advantage is that by focusing on growth rate you tend to get something that grows exponentially.

YC doesn’t explicitly tell founders that with growth rate “you get out what you put in,” but it’s not far from the truth. And if growth rate were proportional to performance, then the reward for performance p over time t would be proportional to pt.

Even after decades of thinking about this, I find that sentence startling.

Whenever how well you do depends on how well you’ve done, you’ll get exponential growth. But neither our DNA nor our customs prepare us for it. No one finds exponential growth natural; every child is surprised, the first time they hear it, by the story of the man who asks the king for a single grain of rice the first day and double the amount each successive day.

What we don’t understand naturally we develop customs to deal with, but we don’t have many customs about exponential growth either, because there have been so few instances of it in human history. In principle herding should have been one: the more animals you had, the more offspring they’d have. But in practice grazing land was the limiting factor, and there was no plan for growing that exponentially.

Or more precisely, no generally applicable plan. There was a way to grow one’s territory exponentially: by conquest. The more territory you control, the more powerful your army becomes, and the easier it is to conquer new territory. This is why history is full of empires. But so few people created or ran empires that their experiences didn’t affect customs very much. The emperor was a remote and terrifying figure, not a source of lessons one could use in one’s own life.

The most common case of exponential growth in preindustrial times was probably scholarship. The more you know, the easier it is to learn new things. The result, then as now, was that some people were startlingly more knowledgeable than the rest about certain topics. But this didn’t affect customs much either. Although empires of ideas can overlap and there can thus be far more emperors, in preindustrial times this type of empire had little practical effect. [Note 2]

That has changed in the last few centuries. Now the emperors of ideas can design bombs that defeat the emperors of territory. But this phenomenon is still so new that we haven’t fully assimilated it. Few even of the participants realize they’re benefitting from exponential growth or ask what they can learn from other instances of it.

The other source of superlinear returns is embodied in the expression “winner take all.” In a sports match the relationship between performance and return is a step function: the winning team gets one win whether they do much better or just slightly better. [Note 3]

The source of the step function is not competition per se, however. It’s that there are thresholds in the outcome. You don’t need competition to get those. There can be thresholds in situations where you’re the only participant, like proving a theorem or hitting a target

It’s remarkable how often a situation with one source of superlinear returns also has the other. Crossing thresholds leads to exponential growth: the winning side in a battle usually suffers less damage, which makes them more likely to win in the future. And exponential growth helps you cross thresholds: in a market with network effects, a company that grows fast enough can shut out potential competitors.

Fame is an interesting example of a phenomenon that combines both sources of superlinear returns. Fame grows exponentially because existing fans bring you new ones. But the fundamental reason it’s so concentrated is thresholds: there’s only so much room on the A-list in the average person’s head.

The most important case combining both sources of superlinear returns may be learning. Knowledge grows exponentially, but there are also thresholds in it. Learning to ride a bicycle, for example. Some of these thresholds are akin to machine tools: once you learn to read, you’re able to learn anything else much faster. But the most important thresholds of all are those representing new discoveries. Knowledge seems to be fractal in the sense that if you push hard at the boundary of one area of knowledge, you sometimes discover a whole new field. And if you do, you get first crack at all the new discoveries to be made in it. Newton did this, and so did Durer and Darwin.

Are there general rules for finding situations with superlinear returns? The most obvious one is to seek work that compounds.

There are two ways work can compound. It can compound directly, in the sense that doing well in one cycle causes you to do better in the next. That happens for example when you’re building infrastructure, or growing an audience or brand. Or work can compound by teaching you, since learning compounds. This second case is an interesting one because you may feel you’re doing badly as it’s happening. You may be failing to achieve your immediate goal. But if you’re learning a lot, then you’re getting exponential growth nonetheless.

This is one reason Silicon Valley is so tolerant of failure. People in Silicon Valley aren’t blindly tolerant of failure. They’ll only continue to bet on you if you’re learning from your failures. But if you are, you are in fact a good bet: maybe your company didn’t grow the way you wanted, but you yourself have, and that should yield results eventually.

Indeed, the forms of exponential growth that don’t consist of learning are so often intermixed with it that we should probably treat this as the rule rather than the exception. Which yields another heuristic: always be learning. If you’re not learning, you’re probably not on a path that leads to superlinear returns.

But don’t overoptimize what you’re learning. Don’t limit yourself to learning things that are already known to be valuable. You’re learning; you don’t know for sure yet what’s going to be valuable, and if you’re too strict you’ll lop off the outliers.

What about step functions? Are there also useful heuristics of the form “seek thresholds” or “seek competition?” Here the situation is trickier. The existence of a threshold doesn’t guarantee the game will be worth playing. If you play a round of Russian roulette, you’ll be in a situation with a threshold, certainly, but in the best case you’re no better off. “Seek competition” is similarly useless; what if the prize isn’t worth competing for? Sufficiently fast exponential growth guarantees both the shape and magnitude of the return curve — because something that grows fast enough will grow big even if it’s trivially small at first — but thresholds only guarantee the shape. [Note 4]

A principle for taking advantage of thresholds has to include a test to ensure the game is worth playing. Here’s one that does: if you come across something that’s mediocre yet still popular, it could be a good idea to replace it. For example, if a company makes a product that people dislike yet still buy, then presumably they’d buy a better alternative if you made one. [Note 5]

It would be great if there were a way to find promising intellectual thresholds. Is there a way to tell which questions have whole new fields beyond them? I doubt we could ever predict this with certainty, but the prize is so valuable that it would be useful to have predictors that were even a little better than random, and there’s hope of finding those. We can to some degree predict when a research problem isn’t likely to lead to new discoveries: when it seems legit but boring. Whereas the kind that do lead to new discoveries tend to seem very mystifying, but perhaps unimportant. (If they were mystifying and obviously important, they’d be famous open questions with lots of people already working on them.) So one heuristic here is to be driven by curiosity rather than careerism — to give free rein to your curiosity instead of working on what you’re supposed to.

The prospect of superlinear returns for performance is an exciting one for the ambitious. And there’s good news in this department: this territory is expanding in both directions. There are more types of work in which you can get superlinear returns, and the returns themselves are growing.

There are two reasons for this, though they’re so closely intertwined that they’re more like one and a half: progress in technology, and the decreasing importance of organizations.

Fifty years ago it used to be much more necessary to be part of an organization to work on ambitious projects. It was the only way to get the resources you needed, the only way to have colleagues, and the only way to get distribution. So in 1970 your prestige was in most cases the prestige of the organization you belonged to. And prestige was an accurate predictor, because if you weren’t part of an organization, you weren’t likely to achieve much. There were a handful of exceptions, most notably artists and writers, who worked alone using inexpensive tools and had their own brands. But even they were at the mercy of organizations for reaching audiences. [Note 6]

A world dominated by organizations damped variation in the returns for performance. But this world has eroded significantly just in my lifetime. Now a lot more people can have the freedom that artists and writers had in the 20th century. There are lots of ambitious projects that don’t require much initial funding, and lots of new ways to learn, make money, find colleagues, and reach audiences.

There’s still plenty of the old world left, but the rate of change has been dramatic by historical standards. Especially considering what’s at stake. It’s hard to imagine a more fundamental change than one in the returns for performance.

Without the damping effect of institutions, there will be more variation in outcomes. Which doesn’t imply everyone will be better off: people who do well will do even better, but those who do badly will do worse. That’s an important point to bear in mind. Exposing oneself to superlinear returns is not for everyone. Most people will be better off as part of the pool. So who should shoot for superlinear returns? Ambitious people of two types: those who know they’re so good that they’ll be net ahead in a world with higher variation, and those, particularly the young, who can afford to risk trying it to find out. [Note 7]

The switch away from institutions won’t simply be an exodus of their current inhabitants. Many of the new winners will be people they’d never have let in. So the resulting democratization of opportunity will be both greater and more authentic than any tame intramural version the institutions themselves might have cooked up. Not everyone is happy about this great unlocking of ambition. It threatens some vested interests and contradicts some ideologies. [Note 8]

But if you’re an ambitious individual it’s good news for you. How should you take advantage of it?

The most obvious way to take advantage of superlinear returns for performance is by doing exceptionally good work. At the far end of the curve, incremental effort is a bargain. All the more so because there’s less competition at the far end — and not just for the obvious reason that it’s hard to do something exceptionally well, but also because people find the prospect so intimidating that few even try. Which means it’s not just a bargain to do exceptional work, but a bargain even to try to.

There are many variables that affect how good your work is, and if you want to be an outlier you need to get nearly all of them right. For example, to do something exceptionally well, you have to be interested in it. Mere diligence is not enough. So in a world with superlinear returns, it’s even more valuable to know what you’re interested in, and to find ways to work on it. [Note 9]

It will also be important to choose work that suits your circumstances. For example, if there’s a kind of work that inherently requires a huge expenditure of time and energy, it will be increasingly valuable to do it when you’re young and don’t yet have children.

There’s a surprising amount of technique to doing great work. It’s not just a matter of trying hard. I’m going to take a shot giving a recipe in one paragraph.

Choose work you have a natural aptitude for and a deep interest in. Develop a habit of working on your own projects; it doesn’t matter what they are so long as you find them excitingly ambitious. Work as hard as you can without burning out, and this will eventually bring you to one of the frontiers of knowledge. These look smooth from a distance, but up close they’re full of gaps. Notice and explore such gaps, and if you’re lucky one will expand into a whole new field. Take as much risk as you can afford; if you’re not failing occasionally you’re probably being too conservative. Seek out the best colleagues. Develop good taste and learn from the best examples. Be honest, especially with yourself. Exercise and eat and sleep well and avoid the more dangerous drugs. When in doubt, follow your curiosity. It never lies, and it knows more than you do about what’s worth paying attention to. [Note10]

And there is of course one other thing you need: to be lucky. Luck is always a factor, but it’s even more of a factor when you’re working on your own rather than as part of an organization. And though there are some valid aphorisms about luck being where preparedness meets opportunity and so on, there’s also a component of true chance that you can’t do anything about. The solution is to take multiple shots. Which is another reason to start taking risks early.

The best example of a field with superlinear returns is probably science. It has exponential growth, in the form of learning, combined with thresholds at the extreme edge of performance — literally at the limits of knowledge.

The result has been a level of inequality in scientific discovery that makes the wealth inequality of even the most stratified societies seem mild by comparison. Newton’s discoveries were arguably greater than all his contemporaries’ combined. [Note 11]

This point may seem obvious, but it might be just as well to spell it out. Superlinear returns imply inequality. The steeper the return curve, the greater the variation in outcomes.

In fact, the correlation between superlinear returns and inequality is so strong that it yields another heuristic for finding work of this type: look for fields where a few big winners outperform everyone else. A kind of work where everyone does about the same is unlikely to be one with superlinear returns.

What are fields where a few big winners outperform everyone else? Here are some obvious ones: sports, politics, art, music, acting, directing, writing, math, science, starting companies, and investing. In sports the phenomenon is due to externally imposed thresholds; you only need to be a few percent faster to win every race. In politics, power grows much as it did in the days of emperors. And in some of the other fields (including politics) success is driven largely by fame, which has its own source of superlinear growth. But when we exclude sports and politics and the effects of fame, a remarkable pattern emerges: the remaining list is exactly the same as the list of fields where you have to be independent-minded to succeed — where your ideas have to be not just correct, but novel as well. [Note 12]

This is obviously the case in science. You can’t publish papers saying things that other people have already said. But it’s just as true in investing, for example. It’s only useful to believe that a company will do well if most other investors don’t; if everyone else thinks the company will do well, then its stock price will already reflect that, and there’s no room to make money.

What else can we learn from these fields? In all of them you have to put in the initial effort. Superlinear returns seem small at first. At this rate, you find yourself thinking, I’ll never get anywhere. But because the reward curve rises so steeply at the far end, it’s worth taking extraordinary measures to get there.

In the startup world, the name for this principle is “do things that don’t scale.” If you pay a ridiculous amount of attention to your tiny initial set of customers, ideally you’ll kick off exponential growth by word of mouth. But this same principle applies to anything that grows exponentially. Learning, for example. When you first start learning something, you feel lost. But it’s worth making the initial effort to get a toehold, because the more you learn, the easier it will get.

There’s another more subtle lesson in the list of fields with superlinear returns: not to equate work with a job. For most of the 20th century the two were identical for nearly everyone, and as a result we’ve inherited a custom that equates productivity with having a job. Even now to most people the phrase “your work” means their job. But to a writer or artist or scientist it means whatever they’re currently studying or creating. For someone like that, their work is something they carry with them from job to job, if they have jobs at all. It may be done for an employer, but it’s part of their portfolio.

It’s an intimidating prospect to enter a field where a few big winners outperform everyone else. Some people do this deliberately, but you don’t need to. If you have sufficient natural ability and you follow your curiosity sufficiently far, you’ll end up in one. Your curiosity won’t let you be interested in boring questions, and interesting questions tend to create fields with superlinear returns if they’re not already part of one.

The territory of superlinear returns is by no means static. Indeed, the most extreme returns come from expanding it. So while both ambition and curiosity can get you into this territory, curiosity may be the more powerful of the two. Ambition tends to make you climb existing peaks, but if you stick close enough to an interesting enough question, it may grow into a mountain beneath you.

Notes

There’s a limit to how sharply you can distinguish between effort, performance, and return, because they’re not sharply distinguished in fact. What counts as return to one person might be performance to another. But though the borders of these concepts are blurry, they’re not meaningless. I’ve tried to write about them as precisely as I could without crossing into error.

[1] Evolution itself is probably the most pervasive example of superlinear returns for performance. But this is hard for us to empathize with because we’re not the recipients; we’re the returns.

[2] Knowledge did of course have a practical effect before the Industrial Revolution. The development of agriculture changed human life completely. But this kind of change was the result of broad, gradual improvements in technique, not the discoveries of a few exceptionally learned people.

[3] It’s not mathematically correct to describe a step function as superlinear, but a step function starting from zero works like a superlinear function when it describes the reward curve for effort by a rational actor. If it starts at zero then the part before the step is below any linearly increasing return, and the part after the step must be above the necessary return at that point or no one would bother.

[4] Seeking competition could be a good heuristic in the sense that some people find it motivating. It’s also somewhat of a guide to promising problems, because it’s a sign that other people find them promising. But it’s a very imperfect sign: often there’s a clamoring crowd chasing some problem, and they all end up being trumped by someone quietly working on another one.

[5] Not always, though. You have to be careful with this rule. When something is popular despite being mediocre, there’s often a hidden reason why. Perhaps monopoly or regulation make it hard to compete. Perhaps customers have bad taste or have broken procedures for deciding what to buy. There are huge swathes of mediocre things that exist for such reasons.

[6] In my twenties I wanted to be an artist and even went to art school to study painting. Mostly because I liked art, but a nontrivial part of my motivation came from the fact that artists seemed least at the mercy of organizations.

[7] In principle everyone is getting superlinear returns. Learning compounds, and everyone learns in the course of their life. But in practice few push this kind of everyday learning to the point where the return curve gets really steep.

[8] It’s unclear exactly what advocates of “equity” mean by it. They seem to disagree among themselves. But whatever they mean is probably at odds with a world in which institutions have less power to control outcomes, and a handful of outliers do much better than everyone else. It may seem like bad luck for this concept that it arose at just the moment when the world was shifting in the opposite direction, but I don’t think this was a coincidence. I think one reason it arose now is because its adherents feel threatened by rapidly increasing variation in performance.

[9] Corollary: Parents who pressure their kids to work on something prestigious, like medicine, even though they have no interest in it, will be hosing them even more than they have in the past.

[10] The original version of this paragraph was the first draft of “How to Do Great Work.” As soon as I wrote it I realized it was a more important topic than superlinear returns, so I paused the present essay to expand this paragraph into its own. Practically nothing remains of the original version, because after I finished “How to Do Great Work” I rewrote it based on that.

[11] Before the Industrial Revolution, people who got rich usually did it like emperors: capturing some resource made them more powerful and enabled them to capture more. Now it can be done like a scientist, by discovering or building something uniquely valuable. Most people who get rich use a mix of the old and the new ways, but in the most advanced economies the ratio has shifted dramatically toward discovery just in the last half century.

[12] It’s not surprising that conventional-minded people would dislike inequality if independent-mindedness is one of the biggest drivers of it. But it’s not simply that they don’t want anyone to have what they can’t. The conventional-minded literally can’t imagine what it’s like to have novel ideas. So the whole phenomenon of great variation in performance seems unnatural to them, and when they encounter it they assume it must be due to cheating or to some malign external influence.

(With due credit and sincere appreciation to Paul Graham. His original essay can be read here.)

WHY CORPSES STINK – THE SCIENCE OF SMELL

This great guest post is by Andy Brunning, a UK Chemistry Teacher who hosts the fascinating website Compound Interest at www.compoundchem.com .

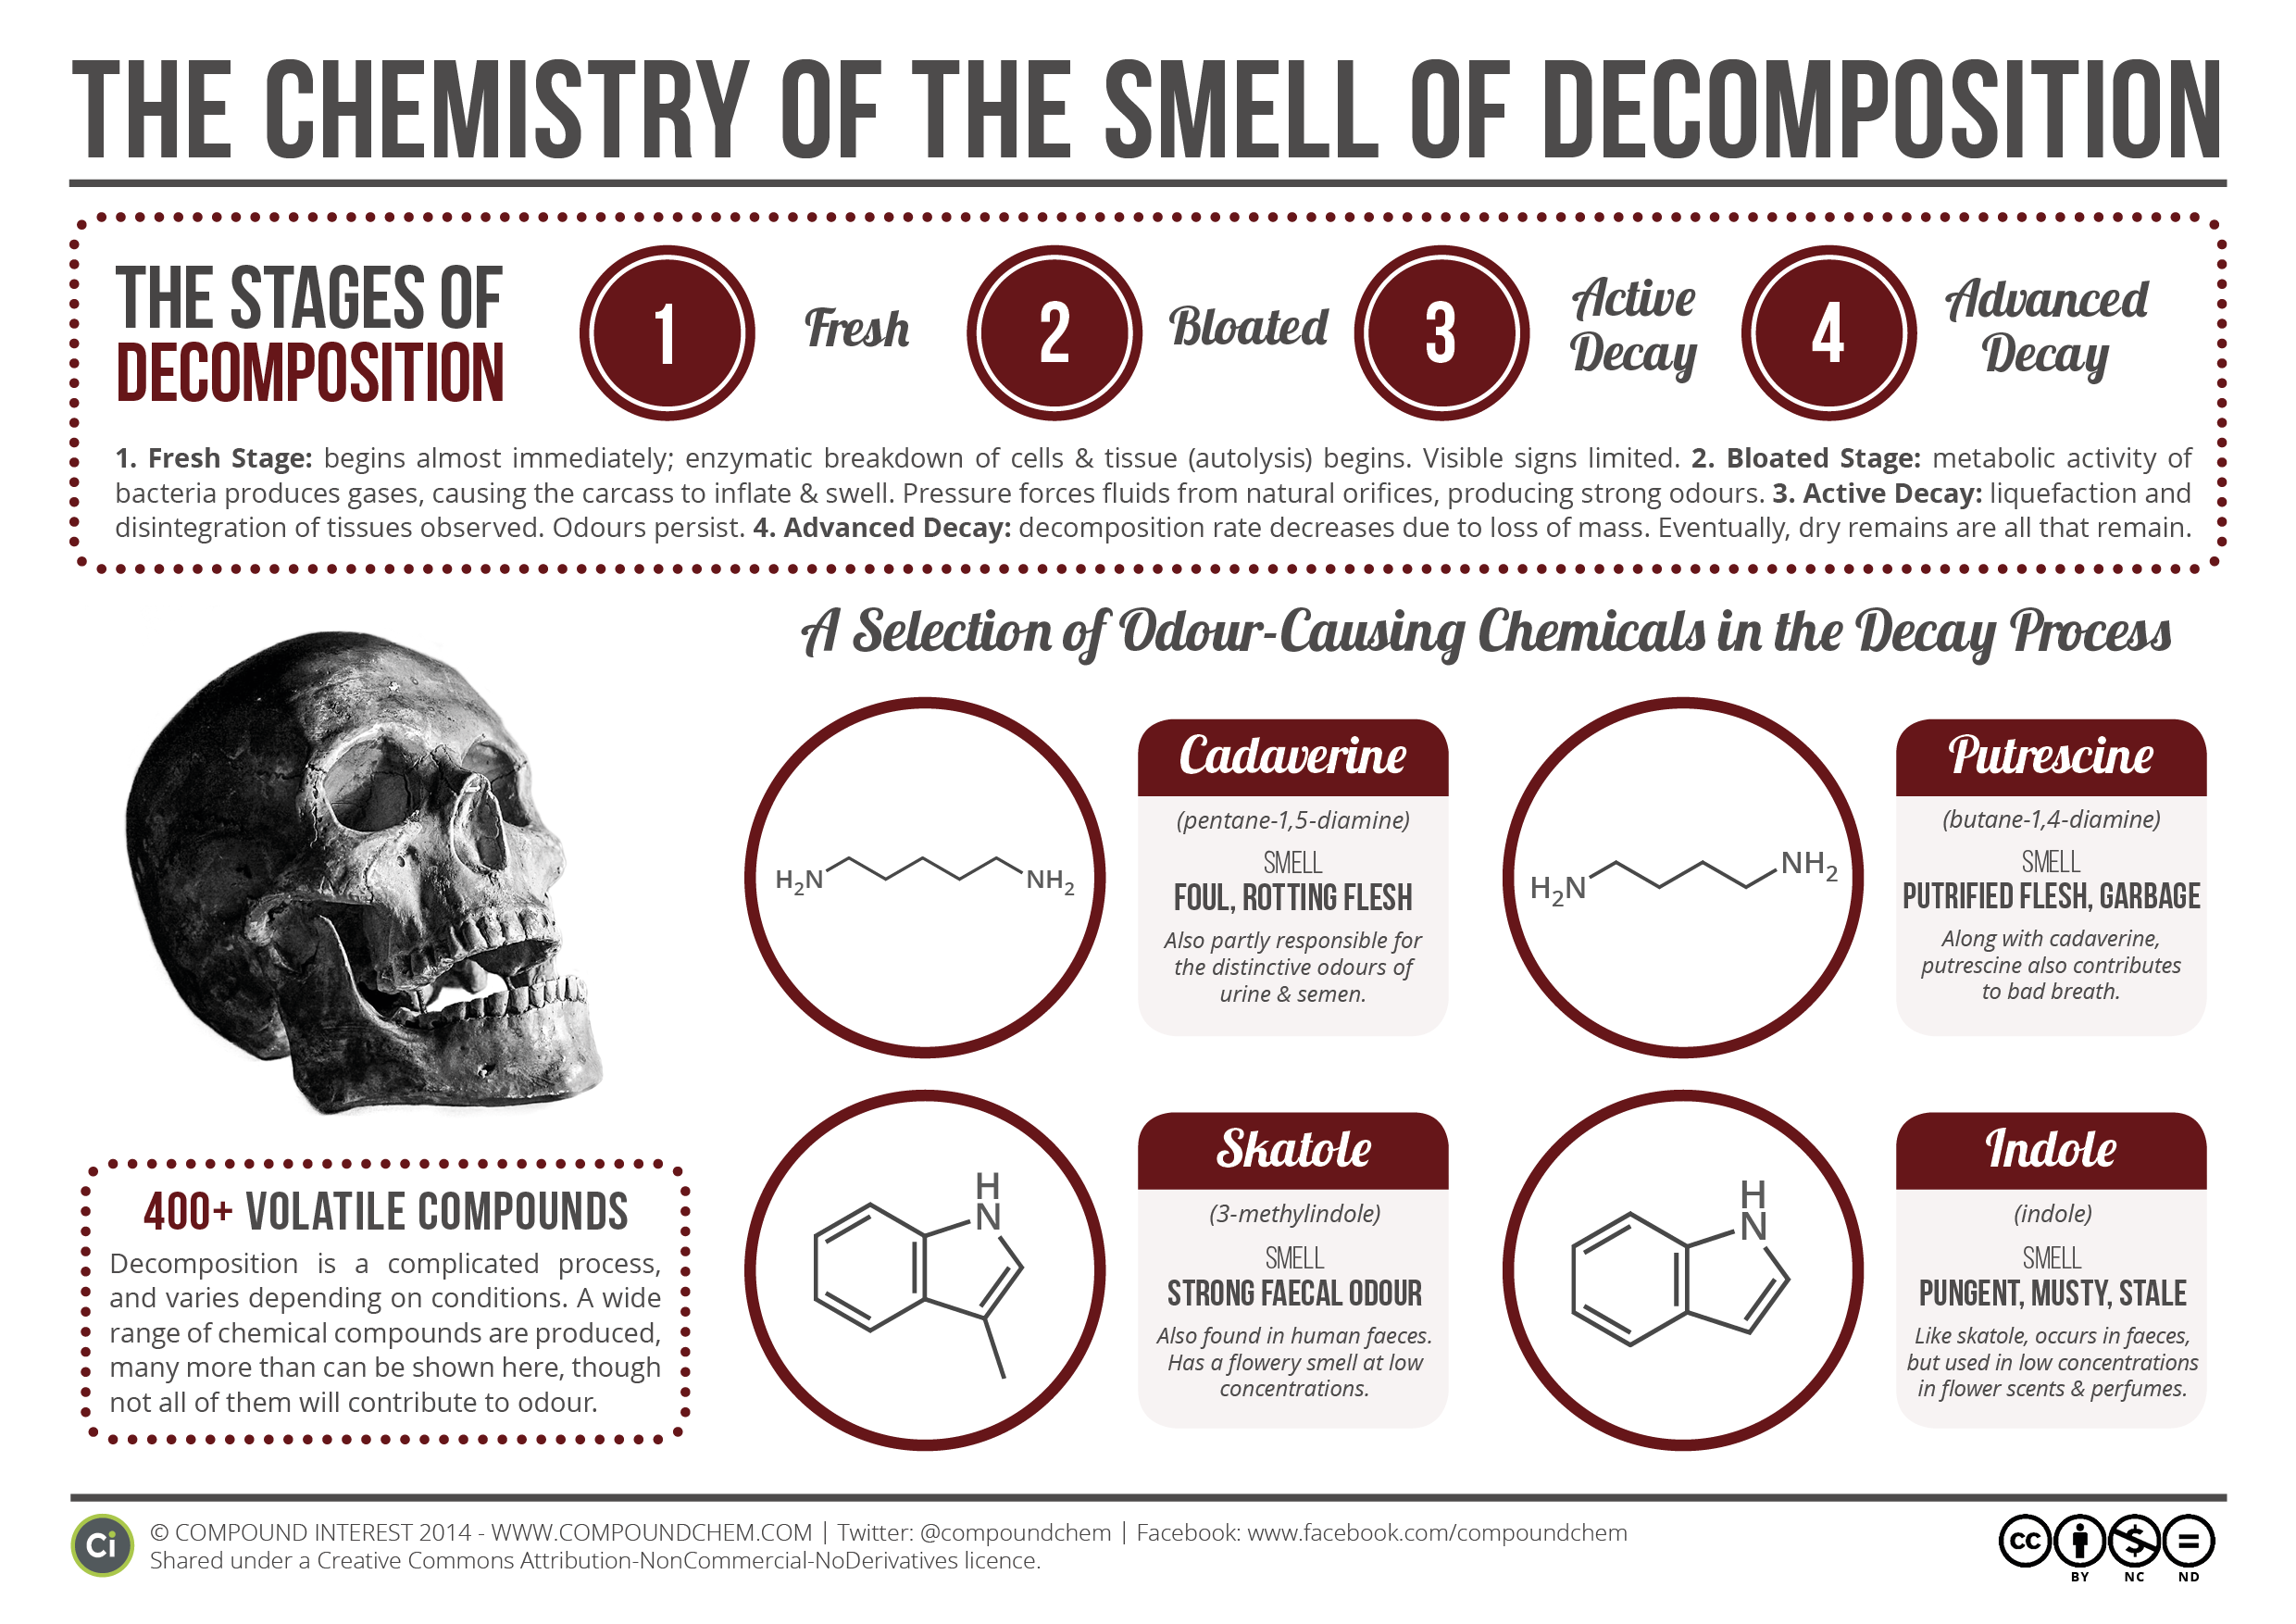
Decomp1Decomposition is an incredibly complicated process, but we do know a little about the chemical culprits behind some of the terrible smells as the body breaks down.

Before we look at specific compounds, it’s worth taking a look at the decomposition process as a whole.

Decomposition, or ‘Decomp’ as it’s called in the death business, can be roughly divided into four stages: the fresh stage, the bloated stage, the active decay stage, and the advanced decay stage. Some overviews of the process also add in a final stage when all that is left of the corpse is dried remains. This can be skeletal, mummification, or fossilization.

The fresh stage of decay kicks off about four minutes after death.

Decomp2Once the heart has stopped beating, the cells in the body are deprived of oxygen. As carbon dioxide and waste products build up, the cells start to break down as a result of enzymatic processes – these are known as autolysis. Initial visual signs of decomposition are minimal, although as autolysis progresses blisters and sloughing of skin may occur.

The second stage of decay occurs as a result of the action of micro-organisms.

The actions of bacteria on the soft tissue of the body produces a variety of gases which cause the carcass to become bloated and swell in size. It’s claimed that the body can as much as double in size during this stage of decomposition. The sulfur-containing compounds that the bacteria release also cause discolouration of the skin, giving it a yellow-green hue.

Decomp3As a result of the bloating, the increased pressure causes bodily fluids to be forced out of natural orifices, as well as potentially causing ruptures in the skin. This can cause a formidable odour; at this stage, if insects are able to access the body, flies will lay eggs in exposed orifices, which will in turn hatch into maggots which then devour the flesh.

The third stage is that of active decay.

At this stage, the ongoing action of bacteria activity and decomposition leads to the liquefaction of tissues, and the persistence of the strong odour. It is during this stage that the cadaver loses the greatest mass.

The final stage, advanced decay, occurs once most of the cadaveric material has already decomposed.

A wide range of factors can affect the decomposition process, including whether the body is buried, and the ambient temperature.

Decomp4These factors also have an effect on the large number of compounds produced during the decomp process. Considering that, as a species, we’ve been dying and decomposing for thousands of years, we know surprisingly little about the specifics of the process and the chemicals involved.

What we do know is that there are several key compounds that contribute towards the characteristic odours of decay.

Two of these are pretty much named for this contribution: cadaverine and putrescine. The aroma of both is loosely described as ‘rotting flesh’, and they have relatively low odour thresholds – meaning that not a lot is required in order for them to make their presence felt by your nostrils. Oddly enough, their presence in your body isn’t limited until after you die, however. Both crop up in cases of oral halitosis (i.e. bad breath), as well as in urine and semen, contributing to their odours.

Two other key compounds are skatole and indole.

Decomp6Skatole, as you may have already guessed from the name, has a strong odour of faeces, whilst indole has a mustier, mothball-like smell. Both compounds are found in human and animal faeces, so it’s little surprise that they can contribute unpleasantness to the odour of a decomposing corpse. The strange thing about both is that, at low concentrations, they actually have quite pleasant, flowery aromas, leading to an array of unexpected uses. Indole is found in jasmine oil, which is used in many perfumes, whilst synthetic skatole is used in small amounts as a flavouring in ice creams, as well as also being found in perfumes.

A range of sulfur-containing compounds also contribute to the smell of decomposition.

Decomp7Produced by the action of bacteria, compounds such as hydrogen sulfide (which smells of rotten eggs), methanethiol (rotting cabbage), dimethyl disulfide (garlic-like) and dimethyl trisulfide (foul/garlic) all add to the unpleasant scent. A whole range of other compounds are also produced as the tissues of the body decompose – some studies have identified over 400 different compounds, although not all of these will be contributors to the odour.

There’s still a lot we don’t know about decomposition.

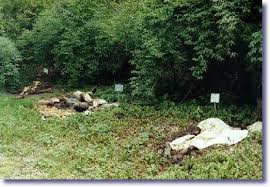
Decomp8Using human corpses in research on decomp is limited in many countries for ethical reasons, so in many studies pigs are used as models. In the USA, however, there are a number of ‘body farms’ – facilities set up in a several states to study decomposition of human remains. The bodies they study are those who have chosen to donate their remains; these are then allowed to decay in a range of conditions and studied as they do so. This can help researchers determine the appearance and chemical emissions of bodies at various stages of decay, which can then inform police investigations where bodies are discovered, helping to determine a more accurate time of death.

Our knowledge about decomposition will develop over the coming years as more studies are carried out.

A particular area of development is looking at producing a method of determining time of death from volatile compound emissions, as the different groups of organic compounds are emitted in varying levels at different stages of the decay process.

Chemistry-of-Decomposition (1)

Compound Interest is a blog by Andy Brunning, a chemistry teacher in the UK, creating graphics looking at the chemistry and chemical reactions we come across on a day-to-day basis.

Decomp10Check out Andy’s fascinating site at www.compoundchem.com